Virtual Card Alternative Payments for Business Invoices Using Request for Payment Accounting
Start sending real-time invoices, receiving good funds, and reconciling faster than ever — all powered by America’s premier real-time merchant processor.
Our mission is to give every business the ability to validate an invoice and choose the most appropriate payment method before funds leave an account. By connecting Request for Payment accounting, virtual cards, RTP®, FedNow®, ACH, Open Banking Positive Pay and automated reconciliation, Real-TimePayments.com helps payers control each obligation from initial request through final accounting.
We believe a payee should be able to send a clear digital payment request while the payer retains authority over the amount, date, account, payment rail and approval process. This structure can improve fraud controls, supplier communication, treasury visibility and payment accountability.
Real-TimePayments.com positions virtual cards as one component of a broader alternative-payment operating system—not as a replacement for every instant-payment or bank-payment use case. The platform connects Digital Positive Pay Invoices, ISO 20022 Request for Payment information, virtual cards, RTP®, FedNow®, ACH, wires, checks, financing and automated accounting through one payer-controlled workflow.
Today Payments provides accounting-centered payment enablement for sole proprietors, professional practices, franchises, property managers, holding companies and multi-state enterprises. The Payer Dashboard helps organizations manage multiple banks, numerous accounts, legal entities, subsidiaries, departments, employees and payment methods without losing centralized authorization control.
Using Business Virtual Cards to reduce Real-Time Cash Liquidity
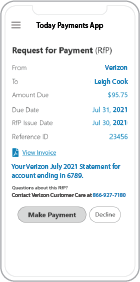
 A supplier may request payment through RTP®,
FedNow® or another electronic payment method, but the payer should
retain control over the final settlement choice. Depending on
treasury policy, available funds, card incentives, payment timing
and supplier acceptance, the payer may decide that a single-use or
limited-use virtual card is more appropriate than the payment method
originally requested.
The Real-TimePayments.com Payer Dashboard
transforms the incoming invoice or Request for Payment into a
controlled authorization decision. Employees can validate the
obligation, compare payment options and recommend an action, while
an authorized administrator selects the final amount, payment date,
funding account and settlement method.
This produces a modern accounts-payable operating principle:
Approve every payment before money leaves your account.
Virtual cards can add merchant restrictions, spending limits, expiration controls and transaction-specific credentials to a business payment. When combined with ISO 20022 Request for Payment information, Reverse Positive Pay and automated reconciliation, they create another way for the payer to control how a valid invoice is settled.
What Is a Virtual Card Alternative Payment for Business Invoices?
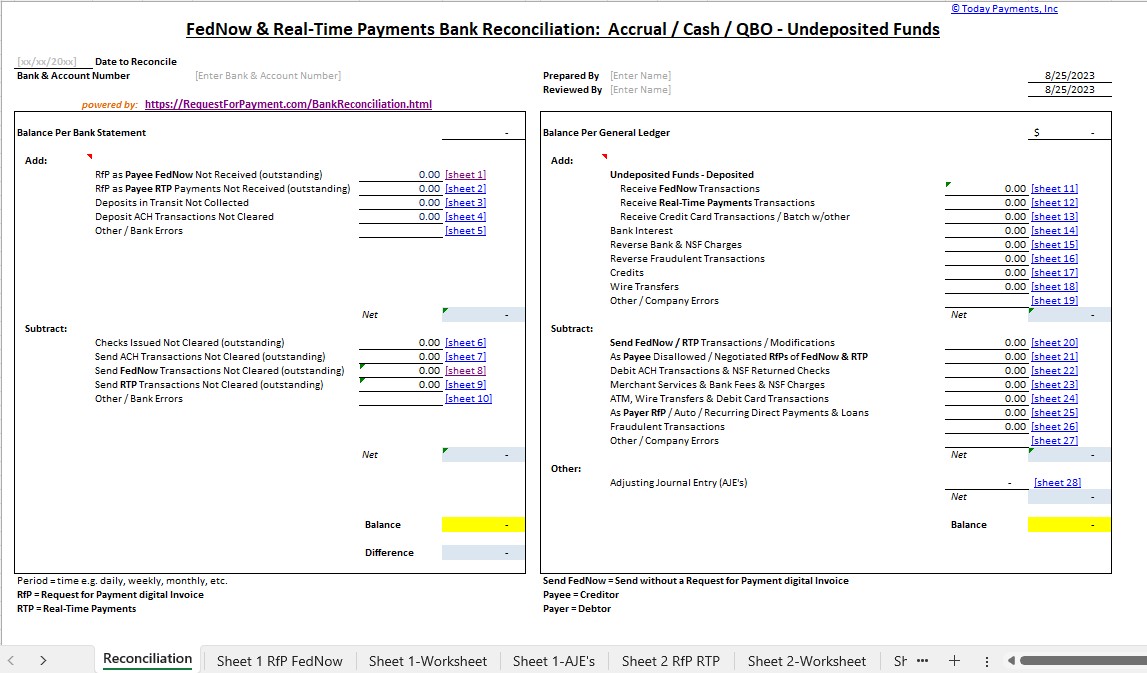
✅ "FREE" Request for Payment Aging & Real-Time Payments Bank Reconciliation – with all merchants process with us.
To support merchants and finance teams of all sizes, TodayPayments.com offers free downloadable templates, including:
- Aging Accounts Receivable Worksheet: Pre-built with 15, 30, 60, 90+ day tracking
- Bank Reconciliation Templates: Instantly match payments with deposits across batches
- ISO 20022 File Format Samples: Plug-and-play structures for batch uploads and RfP™ message testing

✅ "FREE" Real-Time Payments Accounting Pamphlet– with all merchants process with us.
✅ "FREE" QuickBooks® QBO Request for Payment Book – with all merchants process with us.

✅ FedNow® & RTP® Dashboard Positive Pay worksheet – Starting at $25 monthly.
A virtual card is a digitally issued payment credential that can be used instead of a physical plastic card. Depending on the issuer and card program, it may be restricted to one transaction, one payee, a specific amount, a defined date range or a limited number of uses.
In a Request for Payment workflow, the supplier may initially request payment through RTP®, FedNow®, ACH or another method. The payer reviews the invoice and may select a virtual card as an alternative settlement option when the supplier accepts card payments.
A virtual-card workflow can include:
- Invoice validation
- Supplier acceptance confirmation
- Single-use credential generation
- Limited-use credential generation
- Maximum authorized amount
- Merchant or payee restriction
- Expiration date
- Employee approval
- Administrator authorization
- Card-payment delivery
- Processing-fee accounting
- Settlement monitoring
- Invoice reconciliation
- Exception management
The Request for Payment does not itself create or authorize the virtual card. It supplies the business obligation and supporting information that the payer uses to decide how payment should be completed.
How to Pay a Business Invoice with a Virtual Card
Step 1: Receive the Invoice or Request for Payment
The payee sends a digital invoice or Request for Payment containing the requested amount, invoice number, due date, remittance references and applicable payment instructions. The request enters the payer’s Positive Pay Queue.
Step 2: Match the Request with Accounting Records
The accounts-payable employee matches the request with the vendor record, invoice, purchase order, contract and receiving documentation. Missing or conflicting records are placed into an exception workflow.
Step 3: Review the Requested Payment Method
The employee determines whether the payee requested RTP®, FedNow®, ACH, card or another settlement method. The payer can compare the requested method with available alternatives.
Step 4: Confirm Virtual-Card Acceptance
The payer confirms that the supplier can accept the applicable commercial-card network and understands any processing fees or acceptance requirements. A virtual card should not be generated until the payee’s acceptance path is verified.
Step 5: Generate the Virtual Card
The authorized user selects an existing virtual-card program or applies through an eligible issuer or provider. The card may be configured as single-use or limited-use, subject to the program’s capabilities.
Step 6: Establish Payment Controls
The payer can define the maximum amount, approved supplier, expiration date, permitted number of transactions and responsible legal entity. These controls help limit use outside the approved invoice.
Step 7: Deliver the Payment Credential Securely
The virtual-card information is delivered through an approved secure channel. Full card credentials should not be placed in an unprotected email, unrestricted remittance field or public hyperlink.
Step 8: Process and Reconcile the Payment
The supplier processes the virtual-card transaction through its card-acceptance provider. The payer then matches the card authorization, settlement, fees and bank-register entry with the original invoice and Request for Payment.
Open Banking Positive Pay with Multiple Banks and Numerous Accounts
Open Banking Positive Pay allows eligible payment requests and associated accounting records to be reviewed across several financial institutions and funding sources. The payer can preserve separate account ownership and bank permissions while using one dashboard to organize internal decisions.
The Payer Dashboard can classify requests by:
- Bank or credit union
- Card issuer
- Funding account
- Virtual-card program
- Legal entity
- Subsidiary
- Department
- Employee
- Supplier
- Invoice number
- Requested amount
- Due date
- Approval authority
- Payment method
- Risk level
- Settlement status
- Reconciliation status
The administrator can compare available cash, card limits, rewards, rebates, supplier acceptance, fees, timing and internal policy before selecting the final payment method.
Services for Businesses as Payers and Payees
Our services help payees send digital invoices and Request for Payment information while monitoring delivery, payer activity, expected settlement and reconciliation. Payers receive invoice matching, payment-method comparison, virtual-card selection, multi-bank approval workflows, employee sharing, fraud controls and exception management.
Solutions for Businesses as Payers and Payees
Our solutions connect invoices, purchase orders, Request for Payment messages, payer responses, bank accounts, virtual-card credentials, card settlements, instant payments, ACH entries, fees and accounting records. Configurable workflows can support single-use cards, limited-use cards, transaction thresholds, dual approval, partial payments, multiple entities and alternative-payment routing.
Benefits for Businesses as Payers and Payees
Payees gain clearer payment status, more customer payment options and improved invoice-to-settlement visibility. Payers gain increased control over payment credentials, flexible funding choices, potential card-program incentives, stronger employee accountability and detailed reconciliation records.
Features for Businesses as Payers and Payees
Features can include digital invoice intake, Request for Payment creation, virtual-card selection, payment-acceptance checks, employee assignment, role-based approval, payment scheduling, alternative accounts and audit histories. Additional features may include aliases, hyperlinks, QR codes, duplicate detection, supplier verification, settlement tracking, automated reconciliation and RfP™ Aging.
Top 10 Feature-Rich Reasons to Choose Premier FedNow® and RTP®
1. Continuous Instant-Payment Availability
RTP® operates continuously and supports payments at any time through participating institutions. The FedNow® Service similarly enables participating financial institutions to offer instant-payment services outside conventional banking hours.
2. Transactions up to $10 Million
The RTP® network supports individual transactions up to $10 million. The FedNow® Service network transaction limit for customer credit transfers and payment returns also increased to $10 million on November 12, 2025, although individual institutions may impose lower limits.
3. Sender-Controlled Credit Push
RTP® is strictly a credit-push network, meaning the payer instructs its financial institution to send the money. This structure allows the payer to retain control over whether a payment is initiated.
4. Request for Payment Support
RTP® supports Request for Payment messaging that enables billers to send bills and invoices through participating financial institutions while leaving the customer in control of the payment decision.
5. Immediate Settlement
RTP® provides instant and final settlement through its participating financial institutions. That speed increases the importance of validating the supplier and invoice before initiating the transaction.
6. Rich ISO 20022 Information
RTP® supports rich ISO 20022 data that can improve invoice matching and real-time reconciliation. Structured references can connect the payment with the supplier, invoice, purchase order or accounting record.
7. Approve Before Pay Controls
The payer can review the obligation, obtain employee recommendations and retain administrator control before initiating the related payment. The same authorization environment can also allow a virtual card or another alternative method to be selected.
8. Multi-Bank Payer Dashboard
Eligible requests can be consolidated across multiple banks, credit unions, accounts, card programs, legal entities and departments. This provides one operating view while preserving account-level permissions.
9. Alternative-Payment Routing
The payer can compare RTP®, FedNow®, virtual cards, ACH, commercial cards, financing, wires and checks. The choice can be based on speed, finality, cost, incentives, supplier acceptance and internal treasury policy.
10. Automated Reconciliation
The invoice, request, approval, payment credential, settlement record, transaction fee and accounting entry can be linked. Unmatched or disputed items remain in an exception queue until resolved.
Powered by ISO 20022 Request for Payment Messaging
ISO 20022 Request for Payment messaging can carry structured information describing the parties, requested amount, invoice, dates, references and remittance purpose. Businesses can use this information to validate the obligation and choose the appropriate settlement method.
The pain.013 message is associated with the Creditor Payment Activation Request, while pain.014 is the corresponding status-report or response message. A separate pacs.008 credit transfer may be linked to the request when the payer chooses an applicable instant-payment settlement method.
On the RTP® network, the pacs.008 credit-transfer message is the only RTP® message that results in settlement between financial institutions. Selecting a virtual card instead creates a separate card-payment workflow rather than an RTP® settlement transaction.
Digital Payment Authorization Request Table
|
Authorization Decision |
Payer Action |
Accounts-Payable Result |
|
Approve |
Validate the supplier, invoice, amount, account and payment method |
Authorizes the next payment step |
|
Reject |
Decline an incorrect, duplicate, disputed or unauthorized request |
Stops payment and records the reason |
|
Negotiate |
Propose another amount, date, discount, method or installment plan |
Creates a revised-request or exception workflow |
|
Schedule |
Approve payment for a future date |
Moves the request into a scheduled queue |
|
Partial Pay |
Approve less than the requested balance |
Preserves the remaining invoice amount |
|
Virtual Card |
Select or generate an approved card credential |
Routes payment through the card-processing workflow |
|
Change Account |
Choose another eligible funding source |
Routes the payment from a different account or program |
|
Hold |
Pause for documentation or investigation |
Keeps the request pending |
|
Escalate |
Route to a supervisor or administrator |
Requires higher-level authorization |
|
Block or Ignore |
Restrict or flag the sender |
Filters or highlights future requests |
Positive Pay as a Critical Solution for Combating Fraud
Payment fraud can begin before a transaction reaches a bank or card network. False invoices, business email compromise, duplicate billing, supplier impersonation and altered payment instructions can exploit weak accounts-payable procedures.
Positive Pay moves the review to the invoice and Request for Payment stage. The payer can compare the sender with the approved supplier record, validate the purchase order, independently confirm changed instructions and require dual authorization.
Virtual cards can provide additional transaction controls when configured properly. A single-use or limited-use credential may restrict the amount, merchant, expiration period or number of permitted transactions.
Digital Positive Pay can help identify:
- Duplicate invoices
- Duplicate amounts
- New or unfamiliar suppliers
- Changed bank or card instructions
- Missing purchase orders
- Inactive vendors
- Amounts outside historical ranges
- Requests exceeding employee authority
- Conflicts with receiving records
- Unusual payment deadlines
- Requests assigned to the wrong entity
- Multiple attempts to process one virtual card
- Card charges exceeding the approved invoice
- Suppliers that do not accept the selected card network
- Accounts or card programs with insufficient availability
Positive Pay does not eliminate all fraud. It creates a structured control layer that helps detect suspicious obligations before payment is released.
Intelligent RfP™ Routing and Approval Automation
Intelligent RfP™ Routing can examine the payee, invoice, requested amount, due date, legal entity, department, payment history, assigned employee, available bank accounts, virtual-card programs, supplier acceptance and risk indicators. Routine invoices can be assigned to the appropriate employee, while unusual or high-value requests can be escalated.
Approval automation can recommend whether a request should be:
- Paid through RTP®
- Paid through FedNow®
- Paid by virtual card
- Paid through ACH
- Paid by commercial card
- Scheduled
- Partially paid
- Negotiated
- Held for supporting records
- Escalated
- Rejected
- Blocked
Automation should support—not replace—authorized human judgment. The administrator remains responsible for approving the obligation and selecting the payment instruction.
How Intelligent Automation Can Create Value in Real-Time Payments
Intelligent automation can create economic value in the Real-TimePayments.com ecosystem by reducing manual invoice processing, identifying exceptions, improving payment routing and accelerating reconciliation. As FedNow® and RTP® business adoption expands, companies will need stronger systems for determining whether an obligation should be paid instantly, by card, through ACH or by another method.
Potential revenue opportunities include:
- Payer Dashboard subscriptions
- Request for Payment creation
- Virtual-card program referrals
- Virtual-card payment orchestration
- Intelligent payment-method routing
- Fraud-monitoring services
- Multi-bank aggregation
- Approval-workflow subscriptions
- Merchant onboarding
- ISO 20022 file generation
- API subscriptions
- Financing referrals
- Reconciliation services
- Treasury forecasting
- Premium reporting
- White-label payment pages
- RfP™ Aging analytics
The commercial value is not limited to moving money faster. It comes from helping businesses choose the right method, apply the right controls and reconcile the payment efficiently.
Positive Pay Queue: Bank Register for Request for Payments
The Positive Pay Queue can operate as a consolidated bank and payment register for incoming requests, payer decisions and completed transactions. Each record can display the supplier, invoice, requested amount, approved method, funding source, current status and reconciliation result.
Positive Pay Queue Transaction Types
|
Transaction Type |
Payer Dashboard Meaning |
Payment-Rail Meaning |
|
RTP® Debit |
Outgoing RTP® payment reducing the payer’s register balance |
Technically an outbound credit-push transaction |
|
RTP® Credit |
Incoming RTP® payment |
Incoming credit transfer |
|
FedNow® Debit |
Outgoing FedNow® payment reducing the payer’s balance |
Technically an outbound credit-push transaction |
|
FedNow® Credit |
Incoming FedNow® payment |
Incoming credit transfer |
|
Virtual Card Payment |
Invoice paid through a virtual-card credential |
Card-network authorization and settlement |
|
Virtual Card Credit |
Credit, adjustment or refund associated with a card payment |
Card-network credit or adjustment |
|
ACH Debit |
Authorized ACH debit against the account |
Debit-pull entry subject to ACH rules |
|
ACH Credit |
Outbound or incoming ACH credit |
Credit-push ACH entry |
|
Same-Day ACH |
Eligible ACH activity processed on the same banking day |
Qualifying ACH credit or debit |
|
Commercial Card |
Business credit- or debit-card activity |
Card-network transaction |
|
Wire |
Outgoing or incoming wire |
Bank wire settlement |
|
Check |
Issued or cleared paper check |
Check-clearing process |
|
Bank Fee |
Charge posted by a financial institution |
Account-service or payment fee |
|
Card Processing Fee |
Fee associated with card acceptance |
Merchant-acquiring or processing charge |
|
Platform Fee |
Technology or service charge |
Payment-platform fee |
“RTP Debit” and “FedNow Debit” may be used as accounting-register descriptions because the transactions reduce the payer’s balance. RTP® and FedNow® payments are nevertheless sender-initiated credit pushes rather than debit-pull transactions. RTP® is explicitly described as a credit-push network.
Positive Pay Queue Statuses
|
Queue Status |
Meaning |
|
Received |
Request entered the Payer Dashboard |
|
Unreviewed |
No employee has reviewed the request |
|
Viewed |
An authorized user opened the item |
|
Matched |
Request was matched with an invoice or purchase order |
|
Pending |
Waiting for action |
|
Pending Documentation |
Supporting records are required |
|
Pending Employee Review |
Assigned employee has not completed the review |
|
Pending Supervisor Review |
Higher-level approval is required |
|
Approved |
Payer authorized the request |
|
Virtual Card Selected |
Payer selected a virtual-card settlement method |
|
Virtual Card Generated |
Card credential was created |
|
Delivered to Payee |
Approved payment instructions were delivered securely |
|
Authorized |
Card or payment authorization was approved |
|
Partially Approved |
Payer authorized less than the full amount |
|
Negotiation Requested |
Revised terms were proposed |
|
Scheduled |
Payment was approved for a future date |
|
Alternative Payment Selected |
Another account or rail was chosen |
|
Payment Initiated |
Payment instruction was submitted |
|
Completed |
Provider reports successful processing |
|
Reconciled |
Payment was matched with the accounting record |
|
Rejected |
Payer declined the request |
|
Blocked |
Sender was restricted or flagged |
|
Canceled |
Request or payment was canceled |
|
Expired |
Request or card credential reached its expiration |
|
Failed |
Request, authorization or processing failed |
|
Returned |
Eligible ACH or other transaction was returned |
|
Refunded |
Supplier or provider issued a refund |
|
Exception |
Operational or accounting review is required |
Unstructured Remittance Field #1
The Unstructured Remittance field may contain a concise invoice number, supplier reference, purchase-order number, hosted-payment hyperlink, QR destination or alternative-payment instruction. It should supplement structured data rather than replace the required payer, payee, amount and invoice references.
Examples include:
- “Virtual Card Available”
- “Invoice 10254 — Card Payment”
- “Select Single-Use Card”
- “Open Secure Payment Page”
- “Alternative Payment Options”
- “Pay Through RTP®”
- “Select Same-Day ACH”
- “Request Installment Terms”
Full virtual-card credentials should not be inserted into an ordinary unstructured-remittance field. Card numbers, expiration data and security information should be delivered through an approved secure method.
The permitted field length and character set depend on the ISO 20022 message version, network, financial institution, processor and implementation guide. The selected provider’s technical specification should be validated before relying on a universal limit.
Alternative Payment Options
Sometimes the payer wants rights, timing or incentives not offered by the payment method originally requested. The payer may want ACH return rights, payment float, card rewards, rebates, financing, virtual-card controls, installment terms, cross-border capabilities or another funding account.
Exhaustive Alternative-Payment Table
|
Payment Method |
Payer Choices |
Treasury and Accounting Considerations |
|
1. RTP® |
Pay through an eligible participating account |
Immediate settlement, finality, provider limits and account eligibility |
|
2. FedNow® |
Pay through an eligible FedNow® provider |
Participation, limits, account availability and approval controls |
|
3. Virtual Cards |
Use a current virtual card, apply for a program or generate a single-use or limited-use card |
Acceptance, fees, rebates, controls, expiration and reconciliation |
|
4. Business or Owner Cards |
Use a current commercial card, debit card, permitted owner card or new card |
Rewards, payment float, fees, limits and internal policy |
|
5. Same-Day ACH |
Use an existing service or apply through an eligible provider |
Cutoff times, authorization, returns, settlement timing and limits |
|
6. Regular ACH |
Use standard ACH credit, authorized debit or direct payment |
Batch timing, cost, returns and payment float |
|
7. Financing |
Use supplier financing, invoice financing, merchant financing or working capital |
Credit review, fees, interest and repayment terms |
|
8. SNPL — Shop Now Pay Later |
Use standard supplier terms, negotiate installments or apply through a third party |
Payment schedule, financing cost and eligibility |
|
9. Check |
Mail a check to the address included with the request |
Mailing time, fraud risk, stop-payment rights and manual reconciliation |
|
10. Cross-Border Payment |
Use an international-payment or currency-conversion provider |
Foreign exchange, fees, compliance and settlement timing |
|
11. Wire Transfer |
Send from the debtor bank or another authorized payer bank |
Beneficiary verification, fees, cutoff times and finality |
|
12. Other Methods |
MoneyGram, Western Union, QR payment, mobile wallet, stablecoin, cross-border real-time payment, CBDC or future integration |
Availability, acceptance, regulation, custody and reversibility |
Virtual Card Choices
|
Virtual Card Option |
Description |
|
Current Virtual Card |
Use an existing virtual-card relationship |
|
Apply for Virtual Card |
Apply through an eligible issuer or provider |
|
Single-Use Card |
Generate a card restricted to one approved invoice or transaction |
|
Limited-Use Card |
Restrict the amount, supplier, date or transaction count |
|
Exact-Amount Card |
Limit authorization to the approved invoice amount |
|
Time-Limited Card |
Establish an expiration window for payment |
|
Supplier-Limited Card |
Restrict use to the approved merchant or supplier |
Business and Owner Card Choices
|
Card Option |
Description |
|
Current Business Card |
Use an approved commercial-card account |
|
Debit Card |
Fund the payment from an eligible deposit account |
|
Authorized Owner Card |
Use an owner card when company policy permits |
|
New Commercial Card |
Apply through an eligible issuer |
Same-Day ACH Choices
|
Same-Day ACH Path |
Description |
|
Payee Has a Same-Day ACH MID |
Payee uses an eligible Same-Day ACH merchant relationship |
|
Payee Applies for a Same-Day ACH MID |
Payee applies through a participating provider |
|
Payer Uses Existing Same-Day ACH Service |
Payer initiates an eligible ACH credit or authorized debit |
|
Payer Applies for Same-Day ACH Access |
Payer establishes service through a bank, credit union or processor |
The current Same Day ACH per-payment limit remains $1 million. Nacha has approved an increase to $10 million effective September 17, 2027.
Same Day ACH is not an unconditional good-funds guarantee and should not be described as universally irrevocable. ACH entries remain subject to applicable authorization, return and reversal rules.
Regular ACH Choices
|
Regular ACH Path |
Description |
|
Payee Has a Regular ACH MID |
Payee uses an existing ACH merchant relationship |
|
Payee Applies for a Regular ACH MID |
Payee applies for standard ACH processing |
|
Payer Uses Existing ACH Service |
Payer originates an ACH credit or authorized transaction |
|
Payer Applies for ACH Access |
Payer establishes service through a participating provider |
Financing Choices
|
Financing Option |
Description |
|
Invoice Financing |
Financing associated with an eligible invoice |
|
Merchant Financing |
Financing designed for merchant or supplier needs |
|
Working Capital |
Short-term operating funds |
|
Supplier Financing |
Financing offered by or through the payee |
|
New Financing Application |
Application through an eligible third party |
SNPL — Shop Now Pay Later Choices
|
SNPL Option |
Description |
|
Standard Supplier Terms |
Use installment terms already offered |
|
Negotiated Installments |
Request three, six or another number of payments |
|
Third-Party Financing |
Apply through an external installment provider |
B2B and C2B Request for Payment Parameters, Attributes, Benefits and Features
B2B and C2B Request for Payment solutions can include creditor and debtor names, business identifiers, customer and vendor numbers, invoice references, purchase-order numbers, requested amounts, currencies, requested payment dates, expiration dates, structured and unstructured remittance information, aliases, hyperlinks, QR destinations, legal-entity assignments, funding-account choices, virtual-card availability, payment-method options, partial-payment permissions, negotiated terms, recurring-payment indicators, employee assignments, authorization statuses, supervisor escalation, fraud indicators, notification preferences, audit histories, settlement references, card-authorization references, bank fees, card-processing fees and reconciliation data; together, these parameters help businesses improve invoice accuracy, organize accounts payable, accelerate collections, strengthen payer controls, expand payment choice, manage disputes, forecast liquidity, automate A/R and A/P reconciliation, monitor RfP™ Aging and maintain visibility from request creation through final accounting.
Businesses searching for virtual card alternative payments for business invoices can connect supplier invoices with ISO 20022 Request for Payment information, Positive Pay approval and automated accounting reconciliation. Companies using virtual cards with FedNow® and RTP® Request for Payment workflows can compare instant-payment settlement with single-use card controls before choosing how to pay an approved invoice. Organizations implementing Open Banking Positive Pay can manage virtual cards, RTP®, FedNow®, ACH and multiple funding accounts through one multi-bank Payer Dashboard. Enterprises using Intelligent RfP™ Routing and Approval Automation can improve supplier validation, fraud controls, payment-method selection, employee accountability and invoice-to-settlement reporting.
Minimum ISO 20022 Request for Payment Data Fields
Mandatory elements vary by message version, network, participating financial institution and service-provider implementation. A practical minimum business record generally includes the following data.
|
Minimum Data Field |
Business Purpose |
|
Message Identification |
Uniquely identifies the message |
|
Creation Date and Time |
Records when the message was created |
|
Request Identification |
Identifies the individual Request for Payment |
|
Creditor or Payee Name |
Identifies the party requesting payment |
|
Creditor Account or Alias |
Identifies or routes the receiving party |
|
Creditor Agent |
Identifies the payee’s institution or provider |
|
Debtor or Payer Name |
Identifies the party expected to pay |
|
Debtor Account or Alias |
Identifies or routes the payer when required |
|
Debtor Agent |
Identifies the payer’s institution or provider |
|
Requested Amount |
States the requested monetary value |
|
Currency |
Identifies the applicable ISO currency code |
|
Requested Payment Date |
States when payment is requested |
|
Expiration Date or Time |
Defines when the request becomes invalid |
|
Invoice Reference |
Connects the request with the accounting record |
|
Purchase-Order Reference |
Connects the request with the authorized purchase |
|
Remittance Information |
Identifies the order, contract or obligation |
|
Unstructured Remittance |
Carries a brief note, URL or instruction where allowed |
|
Creditor Reference |
Provides a structured payment reference |
|
Legal Entity or Business Unit |
Identifies the responsible organization |
|
Payment-Method Preference |
Identifies a preferred payment rail where supported |
|
Partial-Payment Indicator |
States whether partial payment is permitted |
|
Payment Terms |
Communicates due dates, discounts or installment terms |
|
Response-Routing Information |
Links the payer’s response to the original request |
Virtual-card credentials are separate from these minimum Request for Payment fields and should be generated, protected and delivered through the applicable card issuer or provider.
Sharing Virtual Card Payment Decisions with Employees
Most payers should not generate a virtual card merely because an invoice or Request for Payment was received. The request should first be compared with the invoice, purchase order, contract, receiving record, approved supplier file and company payment policy.
The Payer Dashboard allows employees to review and recommend a payment method while preserving final authority for a designated administrator. The administrator can approve, reject, negotiate, schedule, partially pay, change the account, generate a virtual card or select another settlement method.
|
User Role |
Typical Responsibility |
|
Accounts-Payable Employee |
Match the request with the invoice and purchase order |
|
Department Manager |
Confirm authorization and receipt of goods or services |
|
Subsidiary Manager |
Confirm the responsible legal entity |
|
Controller |
Validate documentation and accounting treatment |
|
Treasury Employee |
Compare bank accounts, card programs, timing, fees and incentives |
|
Fraud Reviewer |
Investigate duplicates, supplier changes and unusual activity |
|
Administrator |
Approve, reject, schedule, reroute or generate the payment method |
|
Owner or Executive |
Authorize payments above established thresholds |
Activity Decisions by a Payer Using ISO 20022 pain.014
The following table describes payer business decisions that may be represented in a Digital Positive Pay environment. Actual pain.014 response codes and supported actions depend on the network and provider implementation.
|
Payer Decision |
Payer Dashboard Activity |
Operational Result |
|
1. Pay — Accept |
Approve the request and select RTP®, FedNow® or another method |
Authorizes the related settlement workflow |
|
2. Decline — Reject |
Reject and record the reason |
Request may be canceled, rejected, expired, failed or redirected to requestforpayment.com/Blog/VirtualCard.html |
|
3. No Action |
Leave the request unanswered |
Request remains open until expiration or timeout |
|
4. Pend |
Retain the item in a queue |
Hold for documentation, supervisor review or a date such as the 1st or 15th |
|
5. Edit Amount |
Approve or propose a different amount |
Creates a partial-payment or negotiated-payment workflow |
|
6. Pay Through Different Account or Alternative Payment |
Select a virtual card, another account or another payment rail |
Routes settlement through the selected provider |
|
7. Block or Ignore Sender |
Restrict, suppress or flag the sender |
Filters or highlights future requests |
A pain.014 message communicates a response or status associated with the Request for Payment. It does not itself generate a virtual card or transfer funds; those actions occur through the applicable card, RTP®, FedNow®, ACH or other payment process.
Reverse Positive Pay Using FedNow® and RTP® vs. Legacy Bank Positive Pay
|
Capability |
Digital Reverse Positive Pay with FedNow®, RTP® and Virtual Cards |
Legacy Bank Positive Pay |
|
Primary Purpose |
Review digital invoices and select an authorized payment method |
Match issued checks or selected ACH records with presented items |
|
Review Timing |
Before the payer initiates settlement |
Usually after an issue file or payment record exists |
|
Request for Payment |
Supported through applicable RfP™ services |
Generally not included |
|
Invoice Validation |
Connects invoices, purchase orders, contracts and supplier records |
Primarily compares transaction details |
|
Virtual-Card Selection |
Can offer single-use or limited-use card settlement |
Generally outside the service |
|
Payment Choice |
Payer chooses the amount, date, account and method |
Normally outside Positive Pay |
|
Multiple Banks |
Eligible requests can be centralized |
Usually managed separately by institution |
|
Alternative Payments |
Can present instant payments, ACH, cards, wires and financing |
Typically outside the workflow |
|
ISO 20022 Information |
Can contain detailed invoice and remittance information |
Often uses limited or proprietary data |
|
Employee Sharing |
Supports assignment, review and escalation |
Usually limited to bank-specific permissions |
|
Administrator Approval |
Final authority remains with the business |
Depends on the institution’s portal |
|
Partial Payments |
May be incorporated into the request workflow |
Generally outside classic Positive Pay |
|
Negotiation |
Can support revised amounts, dates and methods |
Not normally included |
|
Payment Scheduling |
Can be included in the authorization process |
Often handled by another banking service |
|
Aliases and QR Codes |
May include hyperlinks, aliases and payment destinations |
Not a classic Positive Pay feature |
|
Automated Reconciliation |
Links the invoice, request, card or bank payment and accounting record |
Primarily compares issued and presented items |
|
RfP™ Aging |
Tracks pending and completed requests |
Generally not applicable |
|
Sender Controls |
Can flag, ignore or block request senders |
Not normally included |
|
Treasury Forecasting |
Includes pending, approved and scheduled obligations |
Commonly limited to account activity |
|
Fraud Objective |
Detect suspicious obligations before settlement |
Detect exceptions in previously issued payment records |
Automated A/R and A/P Reconciliation
Automated reconciliation connects the invoice or bill, Request for Payment, payer response, virtual-card authorization or bank-payment instruction, settlement record, processing fee and accounting entry. This determines which obligation was satisfied, how much was paid, which funding source was used and whether a remaining balance should remain open.
Matching can use:
- Request identification
- Invoice number
- Supplier record
- Purchase-order number
- Requested amount
- Approved amount
- Card authorization reference
- Card settlement reference
- RTP® or FedNow® settlement reference
- Payment date
- Funding account
- Card-processing fee
- Bank fee
- Accounting entry
Exceptions can be created when the supplier attempts a different amount, processes the card more than once, submits the payment after expiration, deducts unexpected fees or only completes a partial payment.
How to Get Approved for an Interoperable FedNow® and RTP® Merchant Processing Account
Businesses generally access RTP®, FedNow®, Request for Payment, ACH, virtual-card and commercial-card services through participating banks, credit unions, processors, issuers, sponsor relationships or approved fintech providers. Approval and functionality depend on the business model, risk profile, expected activity, bank accounts, providers and intended use cases.
A typical onboarding process may include:
- Complete a merchant or business application.
- Verify the legal business name, EIN, address, ownership and authorized representatives.
- Complete identity, sanctions, Know Your Customer, Know Your Business, fraud and risk reviews.
- Verify each eligible bank account and account owner.
- Identify every entity, subsidiary, division, location, account, MID and card program.
- Describe anticipated volume, average amount, maximum amount and payment purpose.
- Define Request for Payment, Payer Dashboard, API, file and accounting requirements.
- Configure employee roles, approval thresholds, card controls, account permissions and dual authorization.
- Complete message validation, card testing, file testing, API testing and integration testing.
- Obtain production approval from the applicable institutions, issuers and providers.
Real-TimePayments.com specializes in helping businesses prepare for merchant RfP™ activation with multiple MIDs across multiple banks and credit unions throughout all 50 states. Approval, interoperability, virtual-card issuance, file imports, account aggregation, message support and settlement functionality remain subject to participating providers.
Real-TimePayments.com Merchant RfP™ and Alternative-Payment Infrastructure
Real-TimePayments.com is an American accounting fintech merchant processor and payment-technology facilitator—not a bank. We serve as a strategic enabler helping businesses prepare, create, route, authorize, manage and reconcile ISO 20022 Request for Payment, RTP®, FedNow®, virtual-card, ACH, wire, financing and alternative-payment workflows through participating institutions and providers.
We specialize in activating merchant RfP™ relationships with multiple MIDs across multiple banks and credit unions in all 50 states. Whether the business is a sole proprietor or a multi-state enterprise with divisions and subsidiaries, our infrastructure is designed to support aliases, hyperlinks, QR codes, virtual-card options, approval queues, automated A/R reconciliation and RfP™ Aging.
Call us today to discuss the .csv or .xml virtual-card business-invoice, Digital Positive Pay or Request for Payment file your organization needs and begin defining the required data during the initial consultation. Our reporting and integration frameworks are designed to work with participating banks, credit unions, card issuers, processors, accounting systems and payment providers that support the selected message, batch, file or API format. As an early advocate for RequestForPayment.com workflows, we help U.S. businesses prepare structured invoice and alternative-payment information for delivery through approved financial-institution and provider channels.
Although we are not a bank or card issuer, our role as an accounting-system and Open Banking technology provider enables us to help billers and payers prepare Request for Payment, payer-response and virtual-card workflow information for participating banking, card-processing and payment-hub environments. Today Payments’ alternative-payment solution connects applicable pain.013 Request for Payment information and pain.014 response statuses with a separate virtual-card, RTP®, FedNow® or other settlement process, including The Clearing House’s RTP® network when that rail is selected. When implemented through approved providers, this structure can improve processing speed, payment transparency, payer authorization, fraud controls, supplier choice and accounting reconciliation.
Conclusion
A supplier’s preferred payment method should not eliminate the payer’s control. Today Payments’ Accounts Payable Operating System transforms eligible invoices and ISO 20022 Request for Payment messages into structured authorization decisions that can be reviewed, shared, approved, rejected, negotiated, scheduled, partially paid, redirected to a virtual card or blocked before settlement.
The Real-TimePayments.com ecosystem brings together virtual cards, RTP®, FedNow®, Reverse Positive Pay, Open Banking, multiple banks, numerous accounts, employee sharing, administrator approval, alternative-payment routing, fraud controls and automated reconciliation. Payees gain better visibility into the status of their invoices, while payers retain authority over how, when, how much and from which account or card program every obligation should be paid.
From a sole proprietor managing one operating account to a nationwide enterprise coordinating multiple banks, card programs, subsidiaries, employees, MIDs and payment methods, Real-TimePayments.com provides the infrastructure and implementation experience needed to modernize invoice payment.
Request. Review. Choose. Approve. Pay. Reconcile.
Virtual Card Control for Digital Business Invoices.
Choose the Account. Choose the Card. Choose the Rail.
Approve every payment before money leaves your account.
Visit https://www.Real-TimePayments.com to explore virtual-card alternative payments, Digital Positive Pay Invoices, ISO 20022 Request for Payment accounting, FedNow®, RTP®, Reverse Positive Pay, multi-bank authorization and automated reconciliation.
Speak With a Real-Time Payment Specialist NowWhether you’re ready to launch FedNow® & RTP® payments or just exploring options, our team is here to answer your questions and guide you toward the best-fit solution.
Call us now: (866) 927-7180
Or… fill out the quick form below and we’ll contact you within 1 business hour.
Features & Benefits
FedNow® and RTP® instant payments has benefits for all parties involved in
Financial Transactions.
Benefits to your company include:
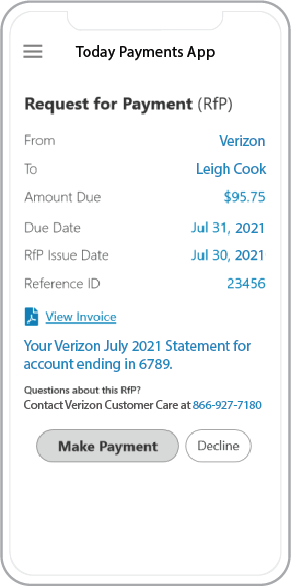 Money Transfer: Current limit of $10,000,000 ~ FedNow®, $10,000,000 ~ RTP®.
It's Fast: 24/7/365 access to funds anytime vs.
several days for paper checks or ACH transfers to process.
Request for Payments ( RfP™ ™): Mobile & Online Real-Time Bill Payments.
It's Final: All Real-Time Payments and Instant Payments are Final & Irrevocable.
Software Integration: Integrate your Management
or Enterprise software with us.
! Secrete Sauce ~ Message Detail: RfP™ – The 145-character unstructured field in ISO 20022 XML messages enables merchants to embed invoice numbers, payer notes, or payment links. ~ Call us now for all the Benefits: Pay FedNow, RTP, ACH, Credit Cards .html links!!
Online Down Payments: Don't use inconvenient
and expensive Wires & Cashier's Checks.
Online Down Payments: Don't use inconvenient
and expensive Wires & Cashier's Checks.
Online Real-Time Reporting: Configured
Dashboard with Virtual Terminal login.
Reduced calls / emails in the "Purchasing Chain": All
parties to a instant payment transaction receive immediately
text & email messaging.
The
FedNow® and RTP® Systems enables Participants to initiate credit transfers,
receive final and irrevocable settlement for credit transfers,
and make available to Receivers funds associated with such
credit transfers in real-time, twenty-four (24) hours a day,
seven (7) days a week, fifty-two (52) weeks a year. All instant payments are "Credit
Push" instead of "Debit Pull."
Creation Request for Payment Bank File
Enhance Your Request for Payment using Real-Time Payments Requests with FedNow’s ISO 20022 Messaging
Streamline Payments with Advanced Request for Payment Options:
Harness the power of FedNow's Request for Payment system to transform how you manage invoices and remittances. Our platform supports diverse data integration options, allowing payees to incorporate detailed invoice data directly within the RfP™ message or link to a comprehensive Merchant Page.
Flexible Invoice Details with ISO 20022 Messaging:
Leverage the flexibility of ISO 20022 messaging standards in our RfP™ system. You can choose to display crucial payment details directly in the message with a concise 145-character description, or through a dynamic "Hyper-Link" leading to a detailed Merchant Page. This Merchant Page can be hosted either on your website "Your Website" - Hosted Payments Page or RequestForPayment.com/RfPHostedPaymentPage.html through our seamless integration solution.
Customizable Merchant Pages for Enhanced Customer Experience:
Create a Merchant Page that not only details all the MIDs you own but also presents these options attractively to your customers through the RfP™. This customization ensures that whether your payer opts for Real-Time Payment, Same-Day ACH, or Card transactions, they can easily navigate and complete their payments through a simple click on the hyperlink provided on your Merchant Page.
Call us today and receive the .csv or .xml FedNow® or Request for Payment (RfP™) file you need—all during your very first phone call! We guarantee that our comprehensive reports integrate flawlessly with your bank or credit union. As pioneers in recognizing the benefits of
RequestForPayment.com, we have stayed years ahead of our competitors. Although we are not a bank, our role as an "Accounting System" within the Open Banking ecosystem enables us to work with billers to create effective RfP™ files that seamlessly upload to the biller's online banking platform. U.S. companies rely on our expertise to learn how to deliver the RfP™ message directly to their bank with precision.
Our advanced solution, Today Payments' ISO 20022 Payment Initiation (PAIN.013), demonstrates how to create a Real-Time Payments Request for Payment file that sends a clear message from the creditor (payee) to its bank. Most financial institutions support the import of messaging and batch files for both FedNow® and Real-Time Payments (RtP), ensuring smooth processing. Once the file is correctly uploaded, the creditor’s bank processes the payment through a secure "Payment Hub"—with The Clearing House serving as the RtP Hub—and relays the message to the debtor's (payer's) bank. This streamlined approach not only accelerates transaction processing but also enhances transparency and reliability for all parties involved.
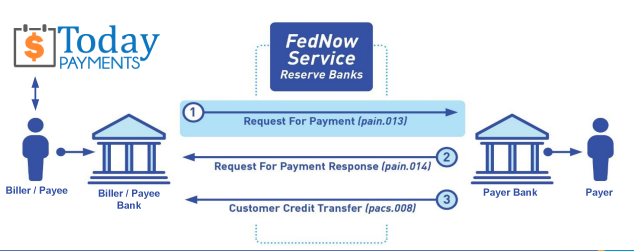
... easily create Real-Time Payments RfP™ files. No risk. Test with your bank and delete "test" files before APPROVAL on your Bank's Online Payments Platform.
Today Payments is a leader in the evolution of immediate payments. We were years ahead of competitors recognizing the benefits of Same-Day ACH
and Real-Time Payments funding. Our business clients receive faster
availability of funds on deposited items and instant notification of
items presented for deposit all based on real-time activity.
Dedicated to providing superior customer service and
industry-leading technology.
Contact Us for Request For Payment payment processing